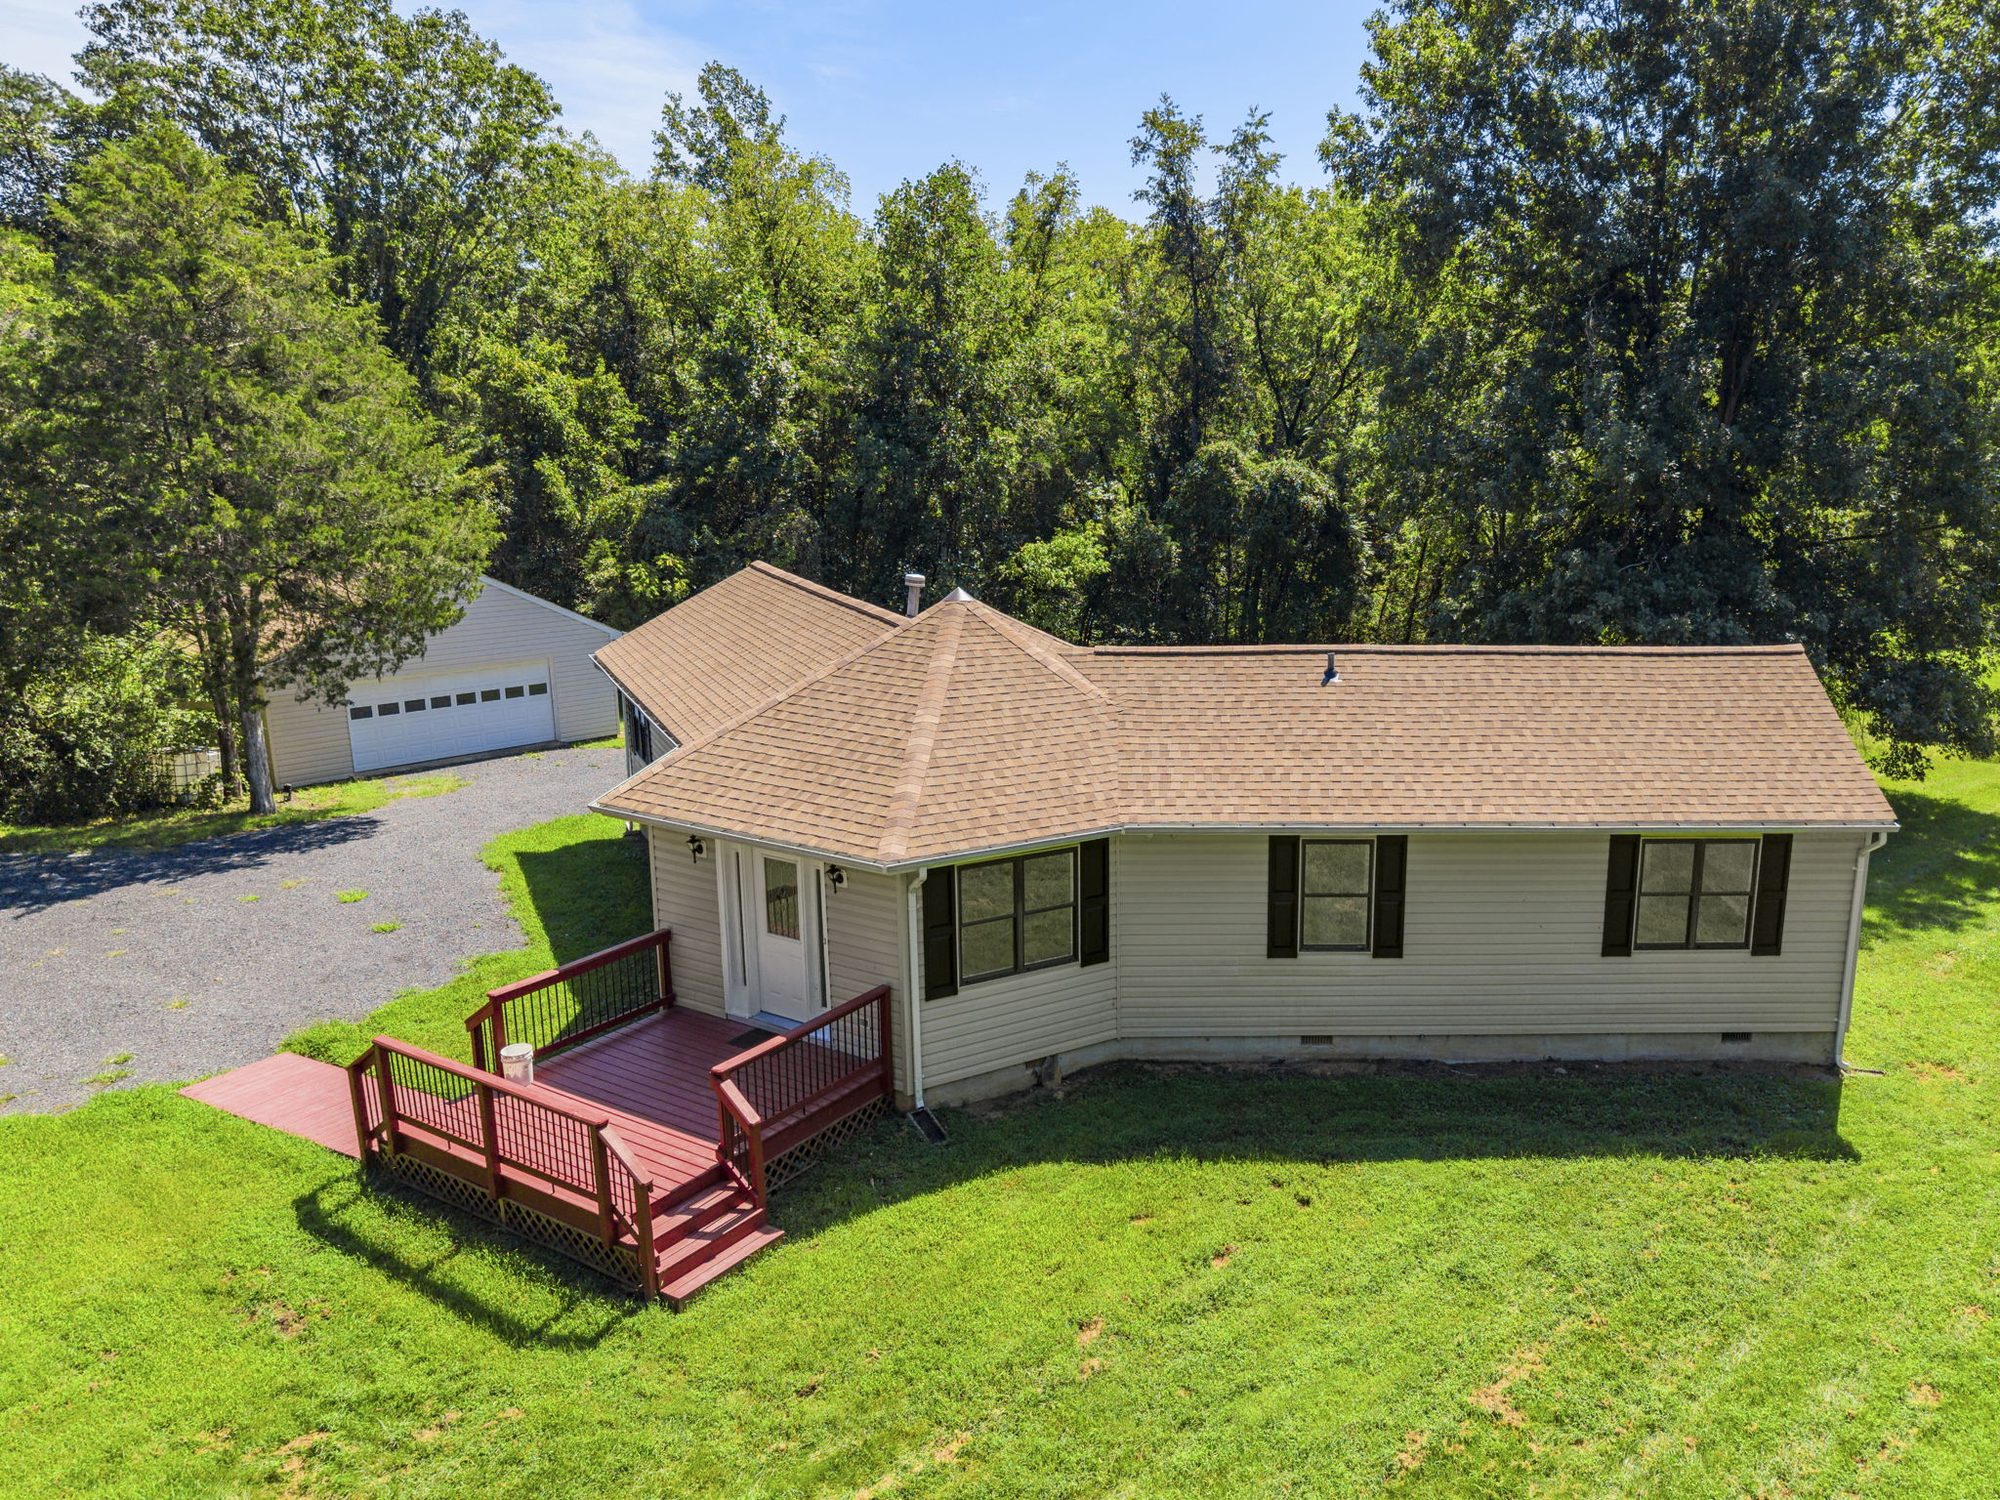
More Paths to 8265 Opal Road Than You Might Think.
$599,000, and likely more ways to get there than you'd expect — VA, USDA, FHA, conventional, or a much larger down payment. Explore the programs below, then try the calculator to see what a payment could look like.
A note on the numbers below: This page is educational only. Chuck Cornwell and CHC Realty are a licensed Virginia real estate brokerage — not a mortgage lender, loan originator, or broker — and nothing here is an advertisement, offer, or commitment to extend credit. Every figure is a hypothetical illustration based on the assumptions you choose, not a quote, pre-approval, or Loan Estimate. Actual rates, APR, program eligibility, and payments are determined by a licensed mortgage lender and change daily. Equal Housing Opportunity.
Explore Your Options
A Program for Nearly Every Buyer.
Every buyer's situation is different. These are some of the more common paths worth discussing with a licensed lender — not an exhaustive list, and not a recommendation of any one program.
VA Loan
For eligible active-duty service members, veterans, and qualifying surviving spouses.
- No down payment required for most eligible borrowers
- No monthly private mortgage insurance (PMI)
- A funding fee typically applies and is usually financed into the loan — it may be reduced or waived for veterans with a qualifying service-connected disability
USDA Rural Development Loan
Backed by the USDA for eligible rural and suburban properties, with income limits based on household size and county.
- No down payment required for eligible buyers
- A low annual guarantee fee replaces traditional PMI
- This address has not been confirmed as USDA-eligible — ask your lender to verify
FHA Loan
Popular with first-time buyers and buyers building or rebuilding credit.
- Down payment as low as 3.5% (10% down for credit scores in the 500–579 range)
- More flexible qualifying guidelines than many conventional programs
- Requires an upfront and annual mortgage insurance premium (MIP)
Conventional Loan
Widely used by buyers with solid credit and some savings for a down payment.
- Some programs allow as little as 3% down for qualifying first-time buyers
- PMI applies below 20% down and can typically be removed once you reach roughly 20% equity
- No government funding fee
Conventional — 20% Down
A traditional path for buyers with an existing home to sell or strong savings.
- No monthly mortgage insurance
- Often the most competitive pricing available
- A strong, straightforward offer in a competitive negotiation
Substantial Down Payment
For buyers bringing significant proceeds from a prior sale, investment funds, or other assets.
- Finance only the remaining half (or less) of the purchase price
- Smaller loan amount and smaller monthly payment
- No mortgage insurance, and a compelling position in negotiations
All-Cash Purchase
No loan, no financing contingency, and typically the fastest path to closing.
- Often the strongest possible offer a seller can receive
- Simpler, faster closing process
- Still worth a conversation with a lender — a cash-out refinance later is always an option
First-Time Buyer & Down Payment Assistance
Virginia Housing and other programs offer down payment and closing cost assistance, plus below-market rate options, for qualifying buyers.
- Income and purchase-price limits apply and vary by program
- Can often be paired with an FHA or conventional loan
- Worth exploring with a participating lender before ruling anything out
Side-by-Side
Quick Comparison.
| Program | Typical Min. Down | Ongoing MI / Fee | Best Fit For |
|---|---|---|---|
| VA | 0% | None (funding fee may apply, often financed) | Eligible veterans, active-duty & surviving spouses |
| USDA | 0% | Annual guarantee fee (~0.35%) | Eligible rural homes, within income limits |
| FHA | 3.5%* | Annual MIP (~0.55%) | First-time buyers & buyers building credit |
| Conventional | As low as 3–5% | PMI if under 20% down (removable) | Buyers with solid credit & some savings |
| Conventional 20%+ | 20% or more | None | Buyers with strong savings or sale proceeds |
| Cash / Large Down | 50%–100% | None | Move-up buyers & buyers prioritizing a strong offer |
*FHA allows 10% down for credit scores in the 500–579 range. All figures are typical ranges, not guarantees, and vary by lender, credit profile, and program guidelines.
See Your Numbers
What Could Your Payment Look Like?
Pick a scenario, or drag the sliders to build your own. This tool is for education and exploration — not a rate quote or loan offer.
Try a Scenario
Defaults to the list price — adjust to model any offer.
Tax defaults to this property's current annual real estate tax bill of $3,500. Property taxes can change after a future Fauquier County reassessment — confirm the current amount with the Commissioner of the Revenue. Insurance is a rough estimate — get an exact quote from an insurance agent.
Conventional Loan · Estimated Example
$4,393/ mo
Estimated total monthly payment
- Loan Amount
- $569,050
- Down Payment
- $29,950 (5.0%)
- Principal & Interest
- $3,691/mo
- Est. Property Tax
- $292/mo
- Est. Homeowners Insurance
- $150/mo
- Est. private mortgage insurance (PMI)
- $261/mo
This is a hypothetical illustration only, not a loan offer, quote, or Annual Percentage Rate (APR) disclosure, and not a commitment to lend. Your actual rate, APR, mortgage insurance, and payment will be provided by a licensed mortgage lender and will vary based on your credit, the program you choose, and market conditions at the time of application.
Illustrative starting rates reflect general market conditions as of early September 2026, when 30-year conventional rates were averaging roughly 6.7%–6.8% (Freddie Mac) and VA rates were running noticeably lower. Mortgage rates change daily and vary by lender — this is not a rate quote or an Annual Percentage Rate (APR) disclosure under the federal Truth in Lending Act.
Outside the Box
Creative Financing for Buyers Who Don't Fit the Mold.
Not every buyer is a W-2 employee with 20% in the bank and no house to sell. Over 40+ years as a licensed Virginia real estate broker, Chuck has seen plenty of transactions come together through structures that never show up on a standard rate sheet. A few worth knowing about — each one still arranged, underwritten, and approved by a licensed lender, not by CHC Realty.
First Trust / Second Trust Combination
Who it's for
Buyers who have the income to qualify but whose down payment is tied up in a home they haven't sold yet.
Two loans close at the same time: a first trust for the bulk of the purchase price and a smaller second trust that covers part of the down payment. The second trust is often paid off in full once the buyer's current home sells — leaving a single, conventional first mortgage behind.
Bridge Loan
Who it's for
Move-up buyers who want to make an offer that is not contingent on selling their current home.
A short-term loan secured by the buyer's existing home (or both properties) that advances the equity needed to purchase before the departing residence closes. The bridge is repaid when that home sells.
DSCR Investor Loan
Who it's for
Buyers purchasing the property as an investment or rental rather than a primary residence.
A Debt Service Coverage Ratio (DSCR) loan qualifies the buyer on the property's expected rental income relative to its proposed payment — not on the buyer's personal tax returns or W-2 income. Typically closed in an individual's name or an LLC.
Bank Statement & Asset-Based Loans
Who it's for
Self-employed buyers, business owners, retirees, and others whose tax returns understate what they can actually afford.
So-called non-QM programs that qualify a buyer using 12–24 months of bank deposits, or by counting liquid assets as income, instead of the standard tax-return review.
Portfolio Loan from a Local Bank
Who it's for
Buyers with an unusual situation — acreage, a recent job change, complex income, or a property feature that trips up standard underwriting.
Community banks and credit unions that keep loans on their own books can write their own guidelines and look at the whole picture rather than a checklist.
These structures are described in general terms only. Availability, terms, rates, fees, and qualifying requirements vary widely by lender and change over time. Some involve higher costs, shorter terms, or additional risk compared with a standard mortgage, and not every lender offers them. Discuss the details with a licensed mortgage loan originator before relying on any of these options.
Also Worth Asking About
A Few More Paths.
- Adjustable-rate mortgages (ARMs) for buyers planning a shorter hold
- Temporary rate buydowns (such as a 2-1 buydown)
- A HELOC against a departing residence to fund a down payment
- Rate buydown points paid at closing in exchange for a lower ongoing rate
Let's Talk Through Your Options.
Every buyer's path is different. Reach out and we'll help point you toward lenders and programs worth exploring for your situation.
Financing Disclosures
The financing information, loan program descriptions, and payment examples on this page are provided for general informational and illustrative purposes only. They do not constitute an advertisement, application, offer, or commitment to make a loan. CHC Realty and Chuck Cornwell are not mortgage lenders, loan originators, or mortgage brokers, and do not take loan applications, set interest rates, or guarantee financing approval, terms, or program eligibility.
Payment examples reflect the down payment, interest rate, loan term, and other assumptions selected using the interactive tool above. They are not an Annual Percentage Rate (APR) disclosure required under the federal Truth in Lending Act (Regulation Z) and do not include all costs of credit. Actual interest rates, APR, mortgage insurance, funding or guarantee fees, closing costs, and monthly payments will vary based on the buyer's credit profile, the lender selected, the specific loan program and its current guidelines, and market conditions at the time of application, and may differ materially from the examples shown. Property tax and insurance estimates are approximate; actual amounts will be confirmed by the local taxing authority and the buyer's insurance carrier.
VA, USDA, FHA, and conventional loan program availability, eligibility (including any property or area eligibility for USDA financing), and terms are determined by the applicable government agency, investor guidelines, and the buyer's individual qualifications — not by CHC Realty. Buyers are strongly encouraged to consult a licensed mortgage loan originator and obtain a written Loan Estimate before relying on any figure shown on this page, and to compare offers from more than one lender.
Equal Housing Opportunity. Under the Equal Credit Opportunity Act, it is illegal to discriminate in any aspect of a credit transaction based on race, color, religion, national origin, sex, marital status, age, receipt of public assistance income, or good-faith exercise of rights under the Consumer Credit Protection Act.